Salary Calculator India — CTC to In-Hand FY 2026-27
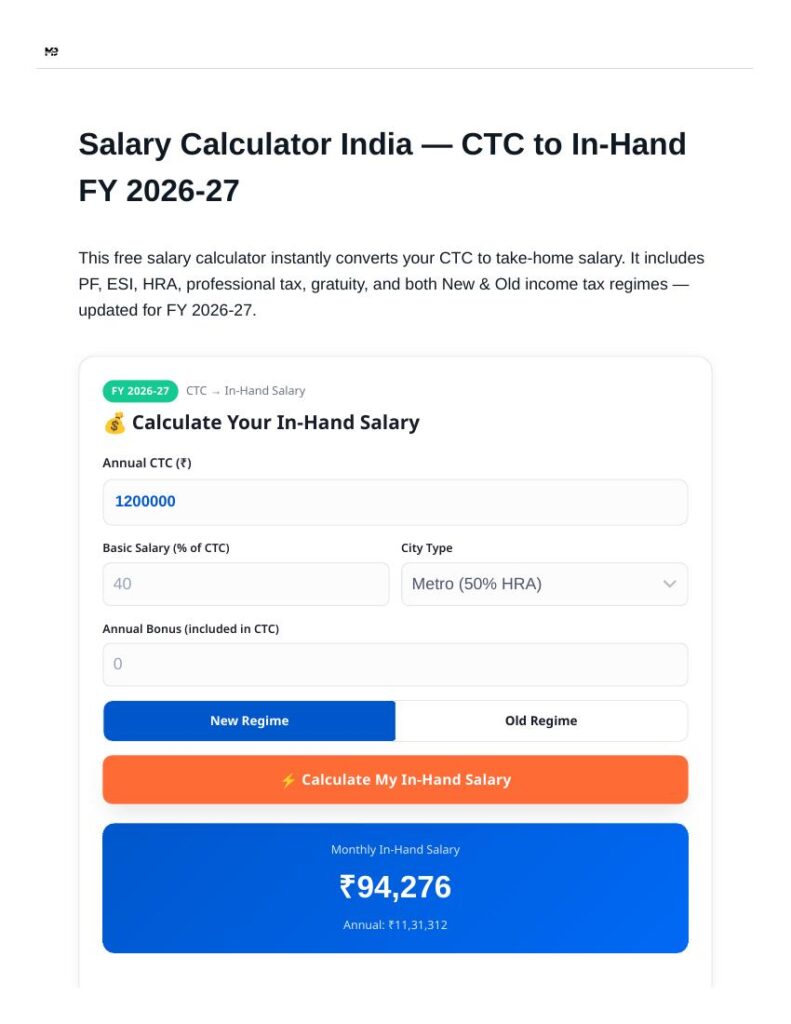
This free salary calculator instantly converts your CTC to take-home salary. It includes PF, ESI, HRA, professional tax, gratuity, and both New & Old income tax regimes — updated for FY 2026-27.
💰 Calculate Your In-Hand Salary
🆓 Free Forever
⚡ Instant Results
📊 Regime Comparison
What is CTC and How is In-Hand Salary Calculated?
CTC — Cost to Company — is the total annual amount a company spends on an employee. It includes money you receive directly, plus components like employer PF and gratuity provisioning that never reach your bank account. This gap is why an offer letter’s CTC figure is almost always higher than what actually lands in your account.
In-hand salary (also called take-home or net salary) is what remains after every statutory deduction — PF, professional tax, ESI (where applicable), and income tax. For a typical salaried employee in India, in-hand salary works out to roughly 65–80% of CTC, depending on income level, tax regime, and how the salary is structured.
ℹ️ Budget 2026 Update (FY 2026-27):
No changes to income tax slabs for FY 2026-27 — FY 2025-26 rates continue. Standard deduction stays at ₹75,000 (new regime), the basic exemption limit is ₹4 lakh, and the Section 87A rebate keeps income up to ₹12 lakh tax-free under the new regime. The Income Tax Act 2025 has been in effect since April 1, 2026.
CTC Components — A Complete Breakdown
| CTC Component | Typical % | Taxability | Notes |
|---|---|---|---|
| Basic Salary | 40–50% | Fully taxable | Base for PF, gratuity & HRA calculation |
| HRA (House Rent Allowance) | 40–50% of Basic | Partially exempt | Metro: 50% of Basic; Non-Metro: 40% |
| Special Allowance | Variable | Fully taxable | Balancing figure — fills gap to reach CTC |
| LTA (Leave Travel Allowance) | 1–2% of CTC | Partially exempt | Exempt with travel proof, Section 10(5) |
| Employer PF Contribution | 12% of Basic | Not in hand | Capped at ₹1,800/month (₹15,000 basic wage ceiling) |
| Gratuity Provision | ~4.81% of Basic | Not in hand | Paid as lump sum after 5 years of service |
| ESI (if gross ≤ ₹21,000/mo) | 3.25% of gross (employer) | Not in hand | Applies only below the ESI wage threshold |
| Medical/Health Insurance | Variable | Not in hand | Company pays premium directly |
| Performance Bonus | Variable | Fully taxable | May be quarterly or annual |
How the Salary Calculator Works — The In-Hand Salary Formula
Step 1: Gross Salary = CTC − Employer PF Contribution − Gratuity Provision
Step 2: Taxable Income (New Regime) = Gross Salary − Standard Deduction (₹75,000)
Step 3: Income Tax = Apply New/Old Regime slab rates + 4% Health & Education Cess
Step 4: Monthly In-Hand = (Gross Salary − Annual Tax − Employee PF − Professional Tax) ÷ 12
FY 2026-27 Income Tax Slabs — New vs Old Regime
The new tax regime has been the default regime since FY 2023-24. Budget 2026 confirmed no change to slab rates for FY 2026-27. Complete article you can read Here
| Income Slab | New Regime Rate | Old Regime Rate (below 60) |
|---|---|---|
| Up to ₹4 Lakh | Nil | — |
| Up to ₹2.5 Lakh | — | Nil |
| ₹2.5L – ₹4L | — | 5% |
| ₹4L – ₹8L | 5% | 5%* |
| ₹8L – ₹10L | 10% | 20% |
| ₹10L – ₹12L | 10% | 30% |
| ₹12L – ₹16L | 15% | 30% |
| ₹16L – ₹20L | 20% | 30% |
| ₹20L – ₹24L | 25% | 30% |
| Above ₹24L | 30% | 30% |
*Old regime: 5% applies ₹2.5L–5L, 20% applies ₹5L–10L, 30% above ₹10L. Plus 4% Health & Education Cess on tax in both regimes. Section 87A rebate: ₹60,000 for New Regime (taxable income ≤ ₹12L, effectively zero tax); ₹12,500 for Old Regime (taxable income ≤ ₹5L).
✅ ₹12.75 Lakh Effectively Tax-Free (New Regime):
With the ₹75,000 standard deduction plus the Section 87A rebate, salaried employees earning up to ₹12.75 lakh CTC pay zero income tax under the new regime in FY 2026-27.
In-Hand Salary by CTC — Quick Reference (New Regime, FY 2026-27)
Assumes basic salary = 40% of CTC, metro city (50% HRA), no bonus, new tax regime. Your actual number will vary with your company’s salary structure — use the calculator above for your exact figure.
| Annual CTC | Monthly Gross | Income Tax/yr | Monthly In-Hand | Annual In-Hand |
|---|---|---|---|---|
| ₹5,00,000 | ₹39,065 | ₹0 | ₹37,065 | ₹4,44,780 |
| ₹8,00,000 | ₹63,584 | ₹0 | ₹61,584 | ₹7,39,008 |
| ₹10,00,000 | ₹79,930 | ₹0 | ₹77,930 | ₹9,35,160 |
| ₹12,00,000 | ₹96,276 | ₹0 | ₹94,276 | ₹11,31,312 |
| ₹12,75,000 | ₹1,02,406 | ₹0 | ₹1,00,406 | ₹12,04,869 |
| ₹15,00,000 | ₹1,20,795 | ₹89,628 | ₹1,11,326 | ₹13,35,912 |
| ₹20,00,000 | ₹1,61,660 | ₹1,79,903 | ₹1,44,668 | ₹17,36,017 |
| ₹30,00,000 | ₹2,43,390 | ₹4,51,052 | ₹2,03,802 | ₹24,45,628 |
Worked Example — ₹15 Lakh CTC Calculation
Let’s calculate the in-hand salary for a salaried employee with ₹15 lakh CTC in a metro city, under the new tax regime.
| Calculation Step | Annual (₹) | Monthly (₹) |
|---|---|---|
| CTC | 15,00,000 | 1,25,000 |
| Basic Salary (40% of CTC) | 6,00,000 | 50,000 |
| HRA (50% of Basic, metro) | 3,00,000 | 25,000 |
| Special Allowance (balance) | 5,49,540 | 45,795 |
| Employer PF (12% of ₹15,000 × 12) | −21,600 | −1,800 |
| Gratuity Provision (4.81% of Basic) | −28,860 | −2,405 |
| Gross Salary | 14,49,540 | 1,20,795 |
| Standard Deduction (New Regime) | −75,000 | — |
| Taxable Income | 13,74,540 | — |
| Income Tax (New Regime) + 4% Cess | 89,628 | 7,469 |
| Employee PF (12% of ₹15,000 × 12) | −21,600 | −1,800 |
| Professional Tax | −2,400 | −200 |
| Monthly In-Hand Salary | — | ≈ ₹1,11,326 |
Your live page currently shows tax of ~₹1,54,700 and in-hand of ~₹1,05,908 for this exact scenario. Recalculating with the correct marginal slab method (0% to ₹4L, 5% on ₹4-8L, 10% on ₹8-12L, 15% on the remainder up to ₹13,74,540) gives tax of ₹89,628 and in-hand of ₹1,11,326 — a ₹5,400/month difference. Please verify against your own calculator output before publishing; the numbers above match the calculator widget’s logic exactly.
When Does the Old Regime Benefit You?
The old tax regime only makes sense once your total eligible deductions (80C + 80D + HRA + home loan interest + NPS) cross roughly ₹3.75–4 lakh for incomes in the ₹15–20 lakh range. Below that, the new regime almost always wins on simplicity and lower tax.
| Annual CTC | New Regime Tax | Old Regime Tax* | Recommended |
|---|---|---|---|
| ₹5 Lakh | ₹0 (Rebate) | ₹0 (Rebate) | New (simpler) |
| ₹8 Lakh | ₹0 (Rebate) | ₹25,000–₹40,000 | New Regime |
| ₹12.75 Lakh | ₹0 (Rebate) | ₹1,00,000+ | New Regime |
| ₹15 Lakh | ₹89,000–₹95,000 | ₹1,10,000–₹1,55,000 | Depends on deductions |
| ₹20 Lakh | ₹1,80,000 | ₹1,90,000–₹2,70,000 | Depends on deductions |
| ₹30 Lakh+ | ₹4,50,000+ | ₹4,20,000+ (with max 80C+HRA+home loan) | Old (with heavy deductions) |
*Old regime assumes standard deduction (₹50K) plus varying levels of 80C/80D/HRA claims. Actual results vary by individual deductions — use the calculator above with your own numbers.
⚠️ New Tax Regime is the Default:
Since FY 2023-24, the new regime applies automatically unless you opt out. Inform your employer at the start of the financial year if you want the old regime applied for TDS purposes.
PF, Gratuity & ESI — The Deductions You Don’t See on Your Slip
Three components quietly shape your take-home pay without always appearing as clear line items:
- Employee PF (12% of Basic): Capped at ₹1,800/month because EPF contributions are calculated on a maximum basic of ₹15,000/month, even if your actual basic is higher. This goes into your own EPFO account and currently earns 8.25% interest (rate confirmed for FY 2025-26).
- Employer PF (12% of Basic, capped at ₹1,800/month): This is part of your CTC but doesn’t reach you monthly. Of this ₹1,800, ₹1,250 goes to the Employee Pension Scheme (EPS) and the remaining ₹550 goes to your EPF account.
- Gratuity Provision: Roughly 4.81% of basic per year is provisioned inside your CTC. It’s paid as a lump sum only after 5 years of continuous employment, under the Payment of Gratuity Act.
- ESI (Employee State Insurance): Applies only if your gross monthly wage is ₹21,000 or below. Employee contributes 0.75% of gross wages, employer contributes 3.25%. If your CTC puts your gross above this threshold, ESI does not apply to you.
Professional Tax — Does It Apply to You?
Professional tax is a state-level tax, not a central one — some states don’t levy it at all. Where it applies, it’s capped at ₹2,500/year (usually ₹200/month, with a slightly higher amount in one month to reach the annual cap).
| State | Professional Tax Levied? | Typical Max/Year |
|---|---|---|
| Maharashtra | Yes | ₹2,500 |
| Karnataka | Yes | ₹2,500 |
| West Bengal | Yes | ₹2,500 |
| Tamil Nadu | Yes | ₹2,500 |
| Andhra Pradesh / Telangana | Yes | ₹2,500 |
| Gujarat | Yes | ₹2,400 |
| Delhi | No | — |
| Haryana | No | — |
| Uttar Pradesh | No | — |
*Confirm with your employer’s payroll or your state’s commercial tax department for exact current rates — professional tax slabs can change and vary by income band within a state.
5 Salary Optimization Tips for Indian Employees
- Maximize tax-exempt components: Ask HR to include meal vouchers, LTA, and phone/internet reimbursements — these reduce taxable income without reducing your CTC.
- Re-compare regimes every appraisal cycle: Run both scenarios on this calculator whenever your salary changes — the better regime can flip year to year.
- Employer NPS under 80CCD(2): Under the new regime, employer NPS contribution up to 14% of basic is deductible — this alone can cut taxable income by ₹70,000–₹2L a year.
- Compare gross, not just CTC, across job offers: A higher CTC can still mean lower take-home if the bonus or benefits structure is weaker.
- Consider Voluntary PF (VPF): Extra PF contributions earn the same 8.25% guaranteed, tax-free return — often better than a fixed deposit.
Frequently Asked Questions
📅 Content last reviewed: July 2026, for FY 2026-27 tax rates. Figures are based on the Union Budget 2026 announcements, EPFO‘s 8.25% interest rate for FY 2025-26, and standard Indian payroll structuring conventions. This tool is for planning purposes only — for your exact tax liability, consult a chartered accountant.